Description
Test a long-or-cash momentum strategy
Original Lingmirage SKILL.md + standalone Python research script. Signal: positive 126-session adjusted-price return. Execute at the following close; otherwise hold cash. One ETF at a time, no leverage, 200-row warm-up.
Download and run
Extract the ZIP, ask your AI assistant to read SKILL.md, and run Python 3.9+ with a licensed Date,AdjustedClose CSV (300+ observations). Outputs JSON: CAGR, total return, drawdown, zero-risk-free Sharpe, entries, equity curve and data SHA-256. Default 10 bps one-way costs including final liquidation; stress at 20 bps. Data and AI subscriptions are not included.
Historical backtest — not live performance
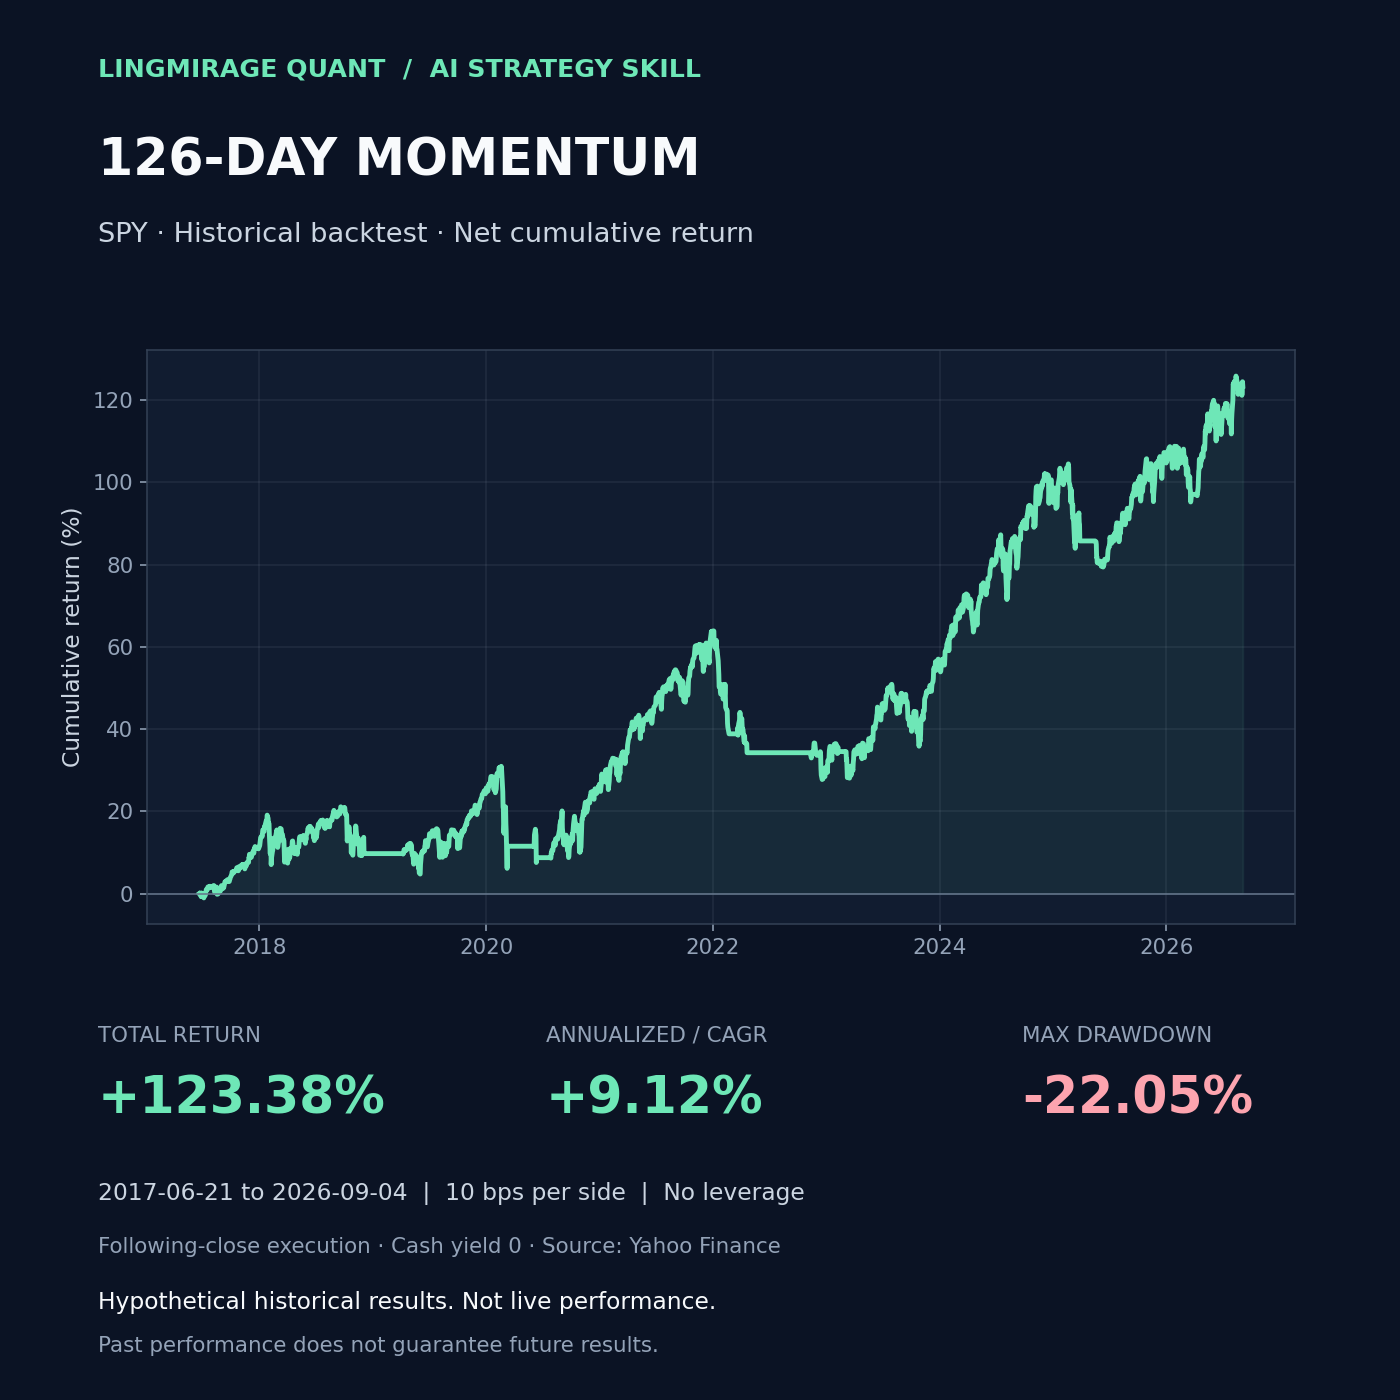
SPY adjusted daily close, Yahoo Finance; 2017-06-21 to 2026-09-04 after a 200-session warm-up. Long/cash, no leverage, next-close execution, cash yield 0%, 10 bps each way including final liquidation. Total return +123.38%; CAGR 9.12%; maximum drawdown -22.05%. Same-period gross SPY buy-and-hold: approximately +264.75%, higher than this strategy.
Retrospective single-market sample, not independent out-of-sample validation. Historical results do not predict future returns. Market data and AI subscriptions are not included.
After purchase
Once payment is confirmed, open My Account → Downloads and download the ZIP. Unzip it, read SKILL.md, and use scripts/quant_backtest.py with Python 3.9+ and your licensed price CSV. This is a research skill, not automated trading or investment advice.
What is inside your ZIP?
- SKILL.md: readable strategy rules and the research workflow for you or an AI coding assistant.
- scripts/quant_backtest.py: standalone Python backtester. No extra Python packages or broker API keys required.
Is this right for you?
For self-directed learners who want to inspect rules and test their own data. You should be comfortable extracting a ZIP, preparing a CSV and running a Python command. An AI coding assistant is optional. This is not a hosted app, live signal feed or automatic trading bot.
Before you buy
Requires Python 3.9+ and at least 300 rows of licensed, split/dividend-adjusted daily prices. Data and AI subscriptions are not included. You can read the skill on mobile or tablet; running the backtest needs a suitable Python environment.
Reviews
There are no reviews yet.